Rapid News Brief
Komatsu announced Nov. 12, 2026, an agreement to buy Astec Industries’ Roadtec and Carlson paving-equipment businesses, which would expand its road-construction product range. Astec’s securities filing puts the cash purchase price at $75 million, subject to adjustments. The agreement would transfer two subsidiaries, not Astec as a whole.
Komatsu CEO Takuya Imayoshi described the deal as further investment in North America, with other markets a longer-term opportunity.
Where the portfolios shift
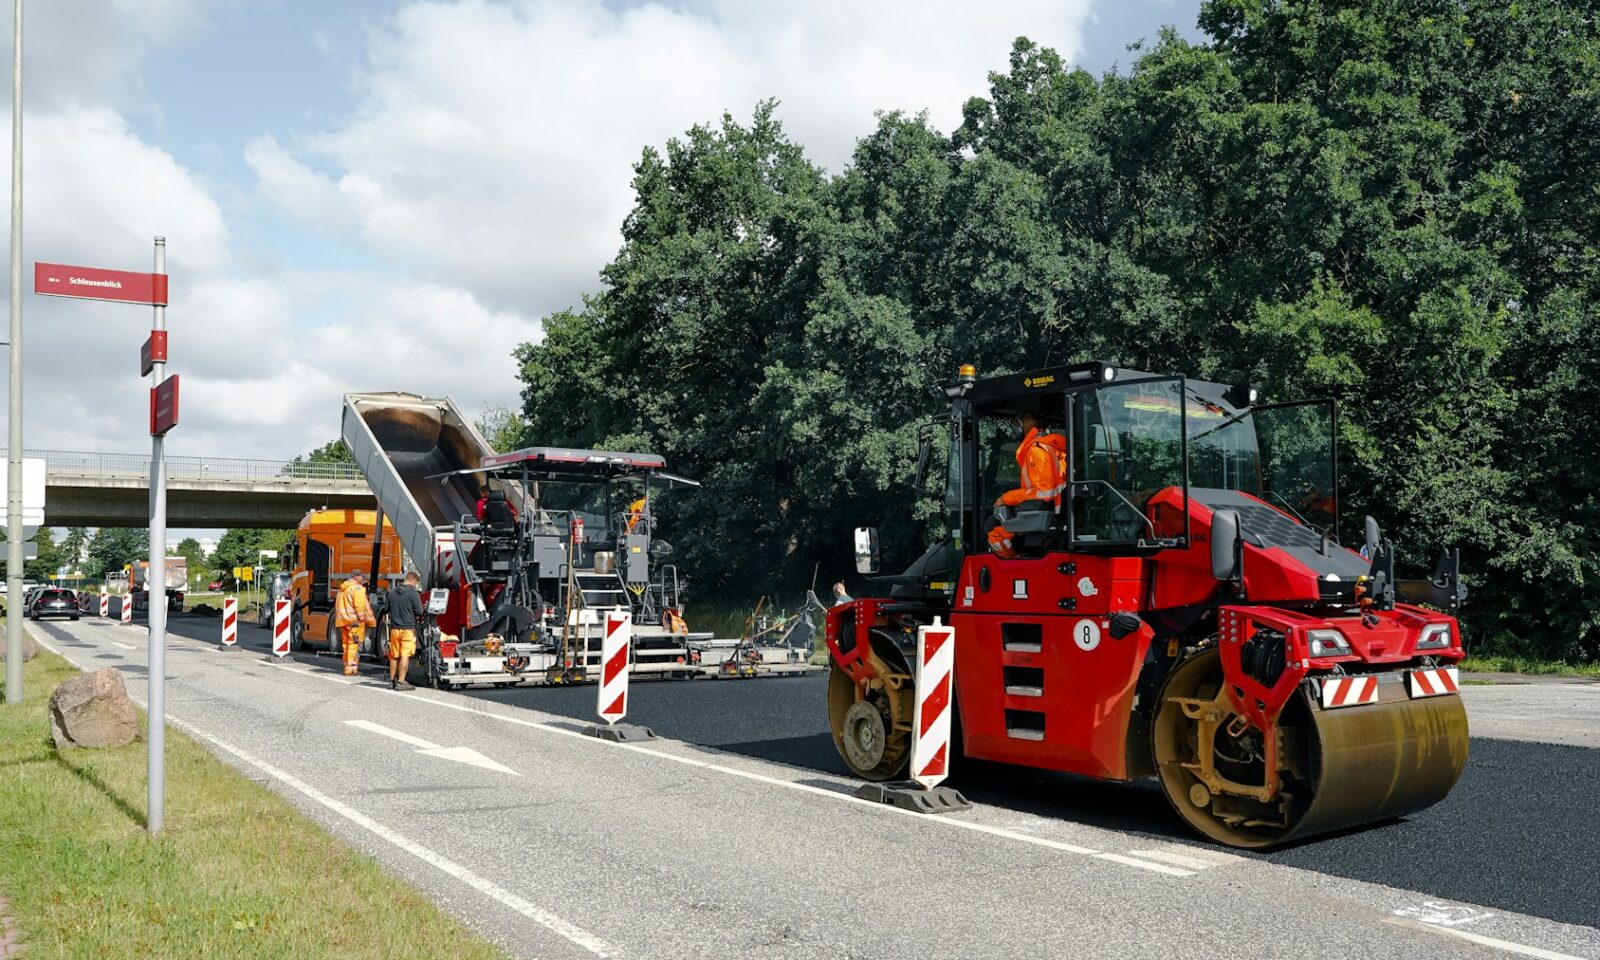
The buyer’s announcement lists pavers, milling machines, material-transfer vehicles and stabilizers among the products the agreement would add. Komatsu said it intends to combine the brands’ specialized technologies with its manufacturing and engineering capabilities. The businesses also provide aftermarket parts and rebuild services, according to Astec. The Roadtec business is based in Chattanooga, Tennessee, Astec said.
Astec said the sale would let it prioritize its core asphalt, aggregates and concrete platforms, alongside opportunities in recycling, digital solutions and mining. The road-equipment business sits within its Infrastructure Solutions segment. Astec’s other manufacturing segment, Materials Solutions, covers aggregate processing, mining and recycling equipment. Astec’s company overview also lists a controls and automation product line.
What must happen before closing
Komatsu expects to close Jan. 1, 2027, subject to customary conditions. Astec’s announcement gives a broader first-quarter 2027 expectation. Its securities filing says the purchase price is calculated on a cash-free, debt-free basis and remains subject to working-capital and other adjustments.
Before closing, Astec must separate the businesses being sold from its retained operations. Conditions also include certain third-party consents and retention agreements with specified employees. The filing describes a transition-services agreement to be entered into at closing. Astec would provide services to the two businesses during a transitional period.
Either side can terminate if closing has not occurred by March 1, 2027, with extensions possible in certain circumstances. That deadline is distinct from the companies’ expected closing window.